This comprehensive guide explores the intricacies of 손해보험, or property insurance, in South Korea. As a crucial aspect of risk management and financial planning, 손해보험 helps individuals and businesses mitigate losses from unforeseen incidents. In Korea’s dynamic economic landscape, having a robust understanding of 손해보험 mechanisms and options enables policyholders to make informed decisions, aligning with personal or corporate needs.
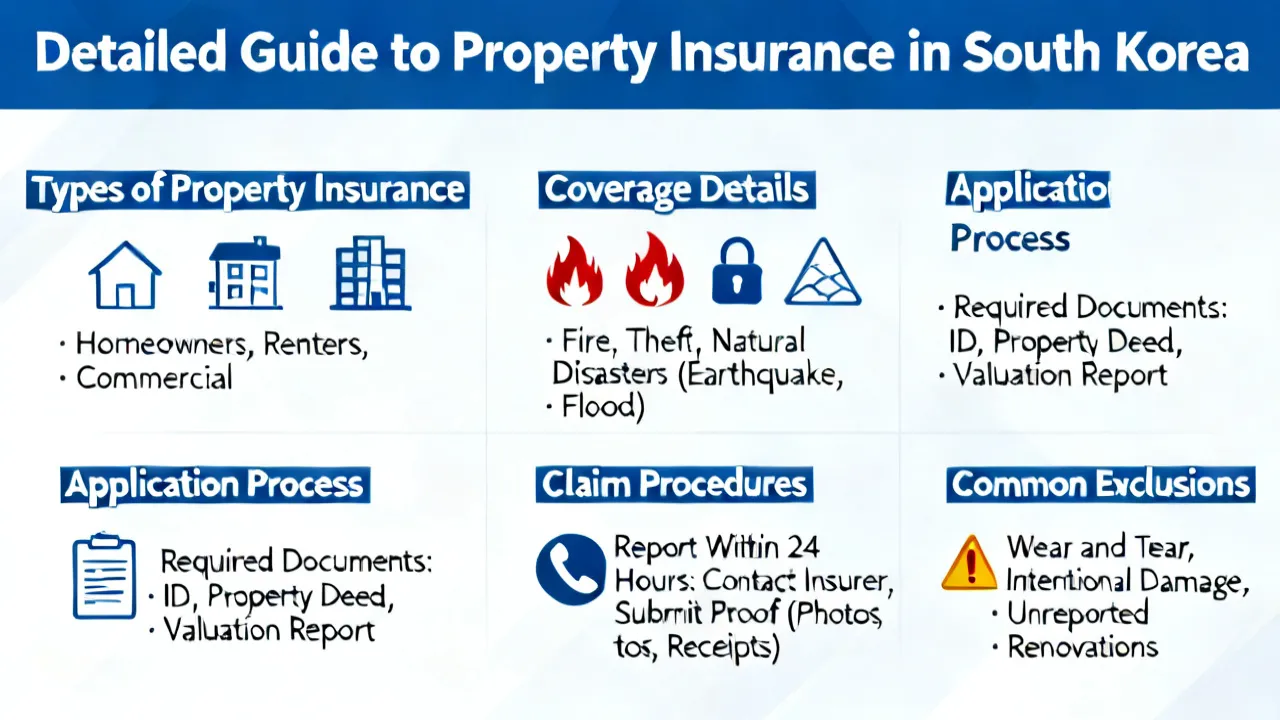
손해보험, or property insurance, plays a vital role in safeguarding the assets and financial wellbeing of individuals as well as businesses in South Korea. By providing coverage against various types of losses and damages, such as those caused by natural disasters, accidents, or theft, 손해보험 ensures that policyholders can recover and rebuild without bearing the full financial burden. South Korea's dynamic economic landscape, coupled with its susceptibility to natural disasters and industrial risks, underscores the necessity of robust property insurance solutions. Without proper coverage, individuals and businesses risk crippling financial strains that could lead to long-term consequences.
In the context of South Korea's rapidly modernizing economy, the importance of 손해보험 cannot be overstated. The country faces diverse risks, ranging from industrial accidents in its burgeoning urban centers to natural calamities such as typhoons and floods. With 손해보험, individuals and companies can protect themselves against significant financial risks, securing both current assets and future growth. The volatile nature of the economy, exacerbated by global uncertainties, further highlights the imperative for comprehensive risk management strategies through property insurance.
손해보험 is categorized into different policies, each tailored to specific needs. Understanding these policy types can help potential policyholders select coverage that aligns with their individual or organizational needs. Here’s a look at some of the most common types:
An in-depth understanding of 손해보험 policies involves examining coverage options, premiums, exclusions, and other pertinent terms outlined in policy documents. It is crucial for policyholders to analyze and understand available options, as well as to assess their own needs and financial conditions when choosing a policy. Additionally, understanding the claims process, limits on coverage amounts, and potential exclusions is equally important for effective decision-making.
When analyzing 손해보험 policies, it's essential to understand the components that determine how coverage works:
The premium rates for 손해보험 policies are influenced by several factors, including:
Selecting an appropriate 손해보험 provider requires careful assessment of the provider's reputation, customer service, claim handling process, and policy flexibility. Considering these aspects ensures that policyholders receive the best possible coverage in case of an emergency. The decision to choose the right insurer also depends on their overall financial stability and the rate at which they settle claims.
| Provider | Key Services | Special Features |
|---|---|---|
| KIA Insurance | Automobile, Fire, Marine | 24/7 claim support, online policy management, specialized theft monitoring. |
| Samsung Fire & Marine | Liability, Marine, Property | Risk assessment tools, customizable plans, fast-track claims process. |
| Hyundai Marine & Fire | Property, Liability, Travel Insurance | Multi-policy discounts, strong customer support, risk management services. |
| DB Insurance | Life, Health, General Liability | Flexible payment options, innovative coverage features, claims assistance. |
Among consumers, there are several misconceptions regarding 손해보험 that can lead to misunderstandings about coverage and claims processes. Some of these include:
What is the typical coverage scope of 손해보험?
Coverage typically includes protection against natural disasters, theft, liability, and accidents, although the specifics vary by policy type.
How can one lower 손해보험 premiums?
Employ safety measures, maintain a good claim history, increase deductibles, bundle multiple policies, and regularly review for competitive offers to potentially lower premiums.
Is 손해보험 mandatory for businesses in South Korea?
While not all types of 손해보험 are legally mandated, certain businesses are required to carry specific types of coverage to protect against liability and operational risks.
Why is 손해보험 important for businesses?
Businesses benefit from 손해보험 as it protects against catastrophic losses that could disrupt operations and financial health. Moreover, it enhances credibility with clients and partners by ensuring risk management is in place.
How do claims processes work in 손해보험?
The claims process typically involves notifying the insurer, completing necessary documentation, providing evidence of loss, and cooperating during the investigation. Prompt reporting is crucial for smoother resolution.
Can 손해보험 policies be customized?
Yes, many insurance providers offer customizable policies to meet specific needs, such as adding riders for specialized coverage or modifying deductibles.
A thorough understanding of 손해보험 is indispensable for individuals and businesses aiming to mitigate risks and secure financial stability in South Korea. The landscape of property insurance is ever-evolving, adapting to new risks presented by globalization and climate change. As one navigates through the diverse options and elements of 손해보험, maintaining an informed perspective allows for strategic decision-making. This aligns with long-term financial goals and risk management frameworks, encouraging policyholders to proactively safeguard their assets and invest in peace of mind as they navigate an increasingly complex world.
The world of 손해보험 is in a continuous state of evolution, influenced by technological innovations, regulatory changes, and emerging risks. Here are some trends shaping the future landscape of property insurance:
Advancements in technology are revolutionizing how insurance companies operate and interact with customers. The introduction of artificial intelligence (AI) and machine learning is enhancing risk assessment and claims handling. For example, AI can analyze patterns from extensive data sets to predict which policyholders might submit claims, allowing insurers to tailor policies and premiums accordingly.
In automobile insurance, telematics is gaining traction. By utilizing GPS and onboard diagnostics, insurers can monitor driving behavior in real-time. Drivers who demonstrate safe driving habits may receive discounts on their premiums, incentivizing responsible behavior.
As cyber threats escalate, businesses are recognizing the need for cyber insurance as part of their risk management strategy. This coverage addresses potential financial losses related to data breaches, cyberattacks, and identity theft, which could otherwise devastate small to medium-sized enterprises without proper safeguards.
As climate change introduces new environmental risks, 손해보험 companies are adapting by offering products that emphasize sustainability. Insurers are starting to consider the environmental impacts of their policies and are providing coverage options that promote green practices, such as discounts for homeowners who utilize energy-efficient materials.
Insurance providers are increasingly moving toward a more personalized approach to policies. Using data analytics, insurers can offer flexible coverage options that consider an individual’s lifestyle and preferences. This shift acknowledges that one size does not fit all and aims to enhance customer satisfaction and retention.
As the insurance landscape evolves, being an informed policyholder becomes even more crucial. Here are some steps policyholders can take to stay educated and make the best decisions regarding their 손해보험:
In summary, understanding 손해보험 is not just about securing financial protection but is also about making strategic decisions that align with personal or business goals. The evolving nature of the insurance sector requires policyholders to be proactive, informed, and adaptable as they navigate their insurance needs. Through careful consideration, research, and engagement with insurance professionals, individuals and businesses can mitigate risks effectively and safeguard their financial futures. In a world characterized by uncertainty, robust 손해보험 is an essential component of a sound financial strategy that fosters resilience and longevity.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

