This article delves into the concept of 적정 보험료, which translates to "appropriate insurance premiums." 적정 보험료 refers to the strategically calculated premium for an insurance policy. In the insurance industry, determining the right premium is crucial for both insurers and policyholders, balancing risk and affordability while ensuring adequate coverage.
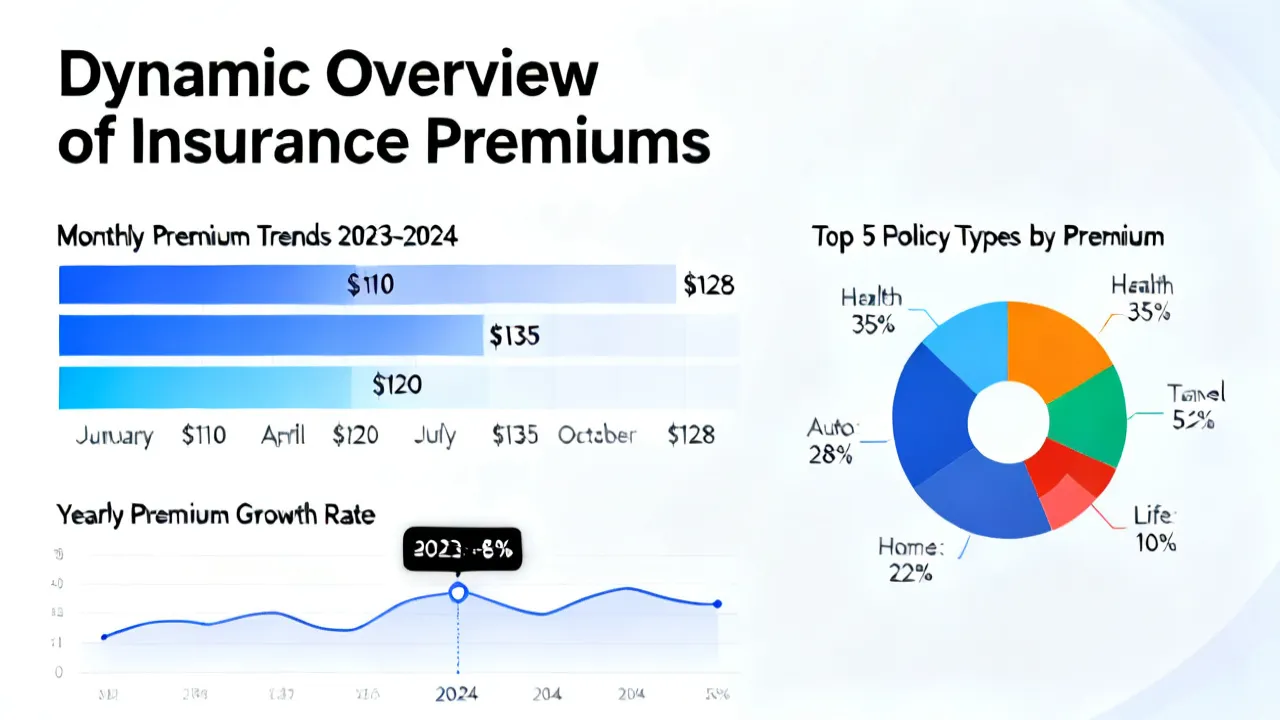
The term "적정 보험료" is central to understanding insurance commitments in the industry. It represents an equilibrium where the cost of an insurance policy is neither excessive nor insufficient for the coverage provided. This concept ensures that policyholders receive fair-priced protection while insurers maintain sustainability in operations. In the ever-evolving landscape of insurance, understanding the intricacies of 적정 보험료 becomes increasingly vital, particularly as consumers become more educated and insurance products diversify.
For both insurers and policyholders, 적정 보험료 plays a crucial role. For insurers, it is essential to calculate premiums to cover potential claims while ensuring profitability. On the other hand, for policyholders, premiums need to be affordable without compromising on the level of coverage they provide. The balance struck by 적정 보험료 serves not only as a foundation for trust between the insurer and the insured but also as a protective measure against unforeseen vulnerabilities.
Moreover, the concept of 적정 보험료 extends beyond immediate financial aspects. It fosters a climate of stability within the insurance market, allowing organizations to plan for long-term risks and liabilities effectively. A system that relies on balanced premiums reduces the likelihood of catastrophic financial events that could arise from poorly calculated insurance products. The significance of 적정 보험료 is thus not limited to individual transactions but reverberates throughout the broader economic framework.
Calculating the 적정 보험료 involves a detailed actuarial analysis. Actuaries use statistical and mathematical models to assess risks and determine the probability of claims. By analyzing historical data and trends, actuaries strive to set premiums that reflect the actual risk level. This sophisticated modeling allows insurers to predict the likelihood of potential losses and adjust pricing accordingly, which is critical for maintaining their financial health.
Moreover, technology plays an increasingly crucial role in this process. With the advent of big data and machine learning, actuaries have access to vast quantities of information that can enhance their predictive capabilities. For instance, telematics in auto insurance, which monitors driving behavior, can lead to more accurately priced premiums based on actual risk rather than generalized statistics. Such innovations make the calculation of 적정 보험료 more precise and aligned with individual circumstances.
| Factor | Impact on Premiums |
|---|---|
| Age of Insured | Older individuals may have higher premiums due to increased health risks. Additionally, younger individuals, often perceived as higher risk drivers, could face elevated auto insurance rates. |
| Geographic Location | Premiums may vary based on location due to differences in local risks and regulations. For example, urban areas with higher crime rates may lead to increased home insurance premiums. |
| Policy Coverage | Comprehensive coverage results in higher premiums compared to basic coverage. Policyholders choosing lower deductibles generally face higher monthly premiums as well. |
| Health Status | Individuals with pre-existing health conditions or lifestyle choices, such as smoking, often pay higher life or health insurance premiums due to elevated risk levels. |
| Claims Experience | A policyholder with a history of frequent claims may face increased premiums as insurers assess them as more likely to claim in the future. |
Policyholders seeking to manage insurance costs while ensuring adequate coverage may consider the following strategies:
Additionally, understanding when to switch insurance providers can be advantageous. As loyalty does not always lead to the best rates, regularly reviewing and shopping for better offers can reveal potential savings and improvements in coverage. The insurance market is continually evolving, and being proactive about one’s policy can yield significant benefits.
As technology advances, the process of determining 적정 보험료 is expected to become even more sophisticated. Emerging tools and technologies like artificial intelligence, machine learning, and enhanced data collection methods can revolutionize risk assessment and premium pricing strategies. Insurers will likely rely on real-time data to inform their underwriting processes, creating more personalized and competitive premiums.
Moreover, the increasing impact of climate change poses new challenges for the insurance sector, making it necessary for insurers to adapt their models accordingly. Weather-related catastrophes have heightened risks for property and casualty insurance, resulting in potential recalibrations of 적정 보험료. Insurers will need to proactively develop products that adequately consider these evolving risks, ensuring that they remain both viable and comprehensive for policyholders.
In conclusion, 적정 보험료 is a pivotal aspect that balances the needs of insurance firms and consumers. A thoroughly evaluated and appropriately set premium ensures that insurance remains a viable and accessible solution for protecting against uncertainties. As the industry evolves, both insurers and policyholders must remain informed about changes that could impact premium calculations. Continuous communication between insurers and consumers will foster an environment of transparency and trust, which is essential for the long-term sustainability of the insurance model.
Ultimately, those engaged in the insurance process — whether as a provider or a policyholder — bear the responsibility of staying informed and adaptive in the face of changes in technology, regulation, and market conditions. By understanding and continuously engaging with the concept of 적정 보험료, both parties can contribute to a healthier insurance ecosystem.




Digital insurance companies, known as 디지털 손해 보험사, are reshaping the insurance landscape by leveraging technology to offer efficient, user-friendly services. These companies differ from traditional insurers by emphasizing digital platforms for operations, creating a seamless customer experience. This article delves into the critical aspects of digital insurance firms, exploring how they function and their benefits to consumers.

This guide delves into the realm of 다이렉트 건강 보험, highlighting its unique structure within the health insurance sector. 다이렉트 건강 보험 is a system that allows consumers to purchase health insurance directly without intermediaries, often resulting in cost savings and tailored plans. This comprehensive analysis explores its benefits, considerations, and frequently asked questions to help consumers make informed choices.

Discover the intricate process of claiming surgery costs under pet insurance (반려동물보험 수술비 청구 방법) to safeguard the health of your cherished furry companions. Pet insurance has become an integral aspect of responsible pet ownership, allowing pet parents to ensure their pets receive optimal medical care without incurring prohibitive costs. This guide provides expert insights into navigating the pet insurance landscape successfully.

This guide delves into 카이저 보험, a renowned name in healthcare provisioning. Known for its integrated care approach and straightforward insurance plans, 카이저 보험 stands as a model of efficiency in health management. By merging medical care services with insurance coverage, it aims to streamline patient experience and ensure accessible, comprehensive healthcare solutions.

As healthcare costs soar globally, mini cancer insurance plans like 미니 암 보험 become crucial for protecting the financial well-being of individuals facing cancer. This coverage, often more affordable than comprehensive plans, provides targeted benefits designed to ease the burden of expenses associated with cancer treatment and recovery. It's essential for consumers to discern their specific needs and compare different offerings.

This article explores the domain of 다이렉트 건강 보험, also known as direct health insurance, to provide a comprehensive understanding of its dynamics and impact on individuals seeking coverage. The discussion delves into the benefits and challenges of opting for direct health insurance, while also touching upon various factors such as cost-effectiveness and accessibility that influence consumer choices in the insurance market.

